Investor Real Estate
Can the Property Support Itself?
A practical introduction to how rental income and debt obligations work together in DSCR underwriting.
By EZ Commercial Capital
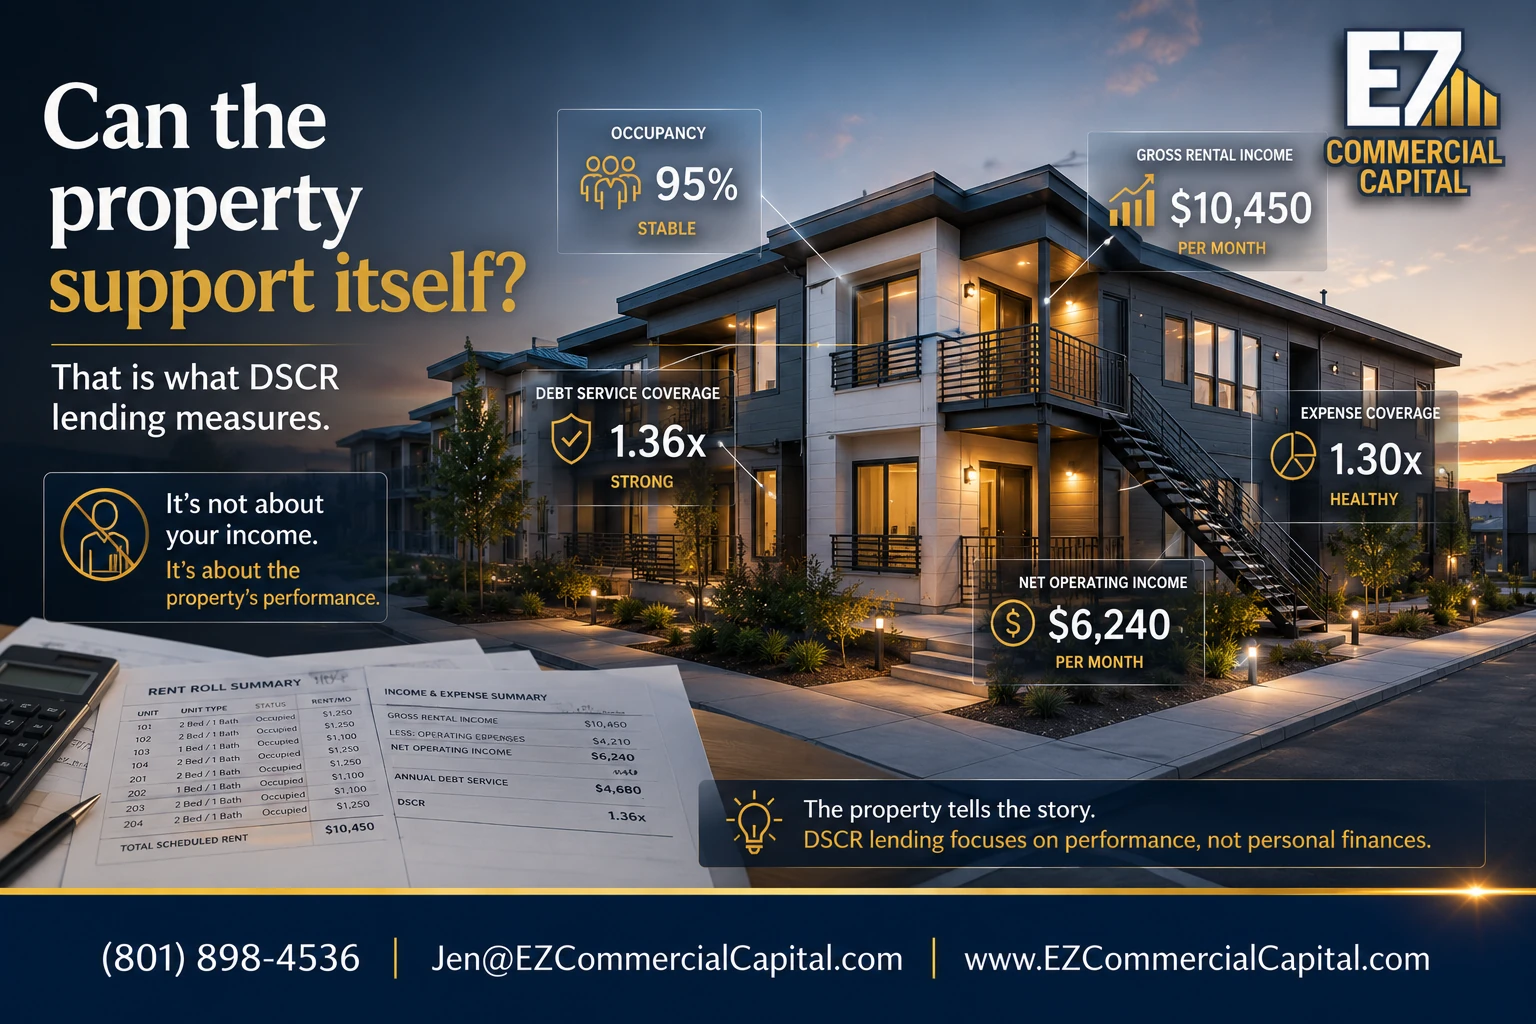
DSCR begins with property cash flow
Debt service coverage ratio compares qualifying property income with the proposed debt obligation. The calculation helps a lender evaluate whether the property can reasonably support its loan payments.
The lender may use lease income, market rent or another approved income method. Taxes, insurance, association dues and other required expenses can materially affect the result.
The ratio is one part of the decision
Credit, liquidity, reserves, property condition, valuation, ownership and loan purpose still matter. A property with strong rent may require a different structure if the borrower plans to occupy it, if repairs are substantial or if the income cannot be documented.
Understanding the complete transaction before selecting a program prevents a simple ratio from creating false confidence.
About the Illustration
The image is a conceptual illustration, not a reconciled loan calculation. Its displayed income, expenses, debt service, and ratios should not be used to size a loan or evaluate an investment. A lender must verify the actual figures and apply its own calculation.