Investor Real Estate
DSCR Loans Explained Simply
Learn how DSCR loans evaluate rental property income, how coverage ratios work, and why credit, reserves, property condition, and guarantees still matter.
By EZ Commercial Capital
Published on the website
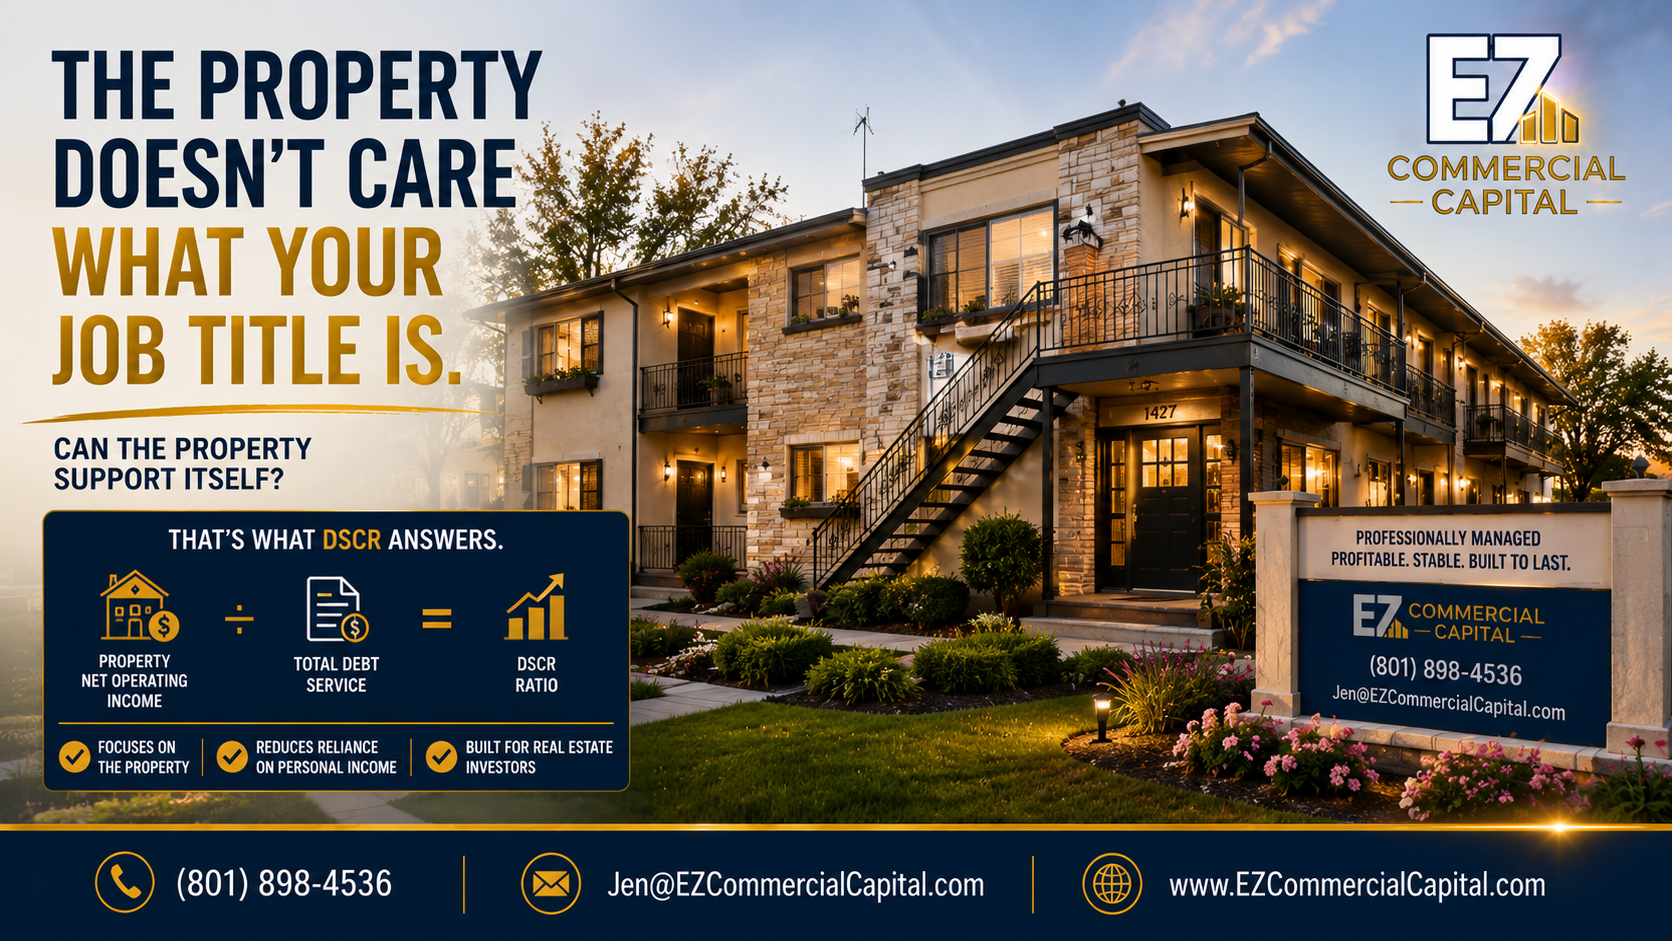
DSCR loans are easier to understand than most people think. They are not based mainly on your personal income. They place substantial emphasis on how the property performs.
That is the key shift. Traditional lending often looks closely at your tax returns, W-2 income, and personal financial history. Many investor DSCR programs instead focus on a different question: Can the property support the proposed payment?
The Property Tells an Important Part of the Story
We worked with a borrower who had strong income, but their tax structure made traditional approval more difficult. On paper, they looked more complex than they actually were.
The property, however, told a simpler story. It produced steady rental income. It had strong occupancy. It covered its expenses comfortably.
In a DSCR loan, property income is central to the qualifying analysis. That does not remove the borrower’s repayment responsibility. Credit, down payment or equity, liquidity, reserves, property condition, and personal guarantees may still affect approval and loan terms.
What DSCR Measures
DSCR stands for Debt Service Coverage Ratio. In simple terms, it compares qualifying property income with the payment obligations the lender includes in its calculation.
Many residential rental DSCR programs divide qualifying monthly rent by principal, interest, property taxes, insurance, and association dues, when applicable. Commercial property underwriting commonly compares net operating income with debt service. The calculation must match the particular program.
When qualifying income provides more coverage, the request may fit more programs or receive different terms. When coverage is weaker, approval can be more difficult. Some programs consider lower coverage with other conditions, so no single ratio guarantees approval or decline.
A Different Way to Think About Approval
Many people assume, “My income is the main issue.” DSCR shifts the focus toward, “How strong is the property itself?”
This can reduce reliance on conventional personal-income documentation for eligible investors. The lender still evaluates the property and the borrower under its program requirements.
Where DSCR Loans Can Work Well
- Rental properties with stable, documented income
- Investors with non-traditional income structures
- Properties that perform better than the borrower’s tax profile suggests
- Eligible transactions where a property-income approach may simplify personal-income documentation
Where Another Structure May Be Needed
- Properties that are not yet stabilized or require substantial repairs
- Income that is inconsistent, unpredictable, or unsupported
- Deals where current coverage does not meet the selected program’s requirements
A transitional property may need renovation or bridge financing before it is ready for a long-term rental loan. Available options depend on the complete transaction.
Start With the Property’s Numbers
At EZ Commercial Capital, the first question is simple: Does the property support the proposed financing on paper? If it does, DSCR financing may deserve consideration alongside the remaining borrower and program requirements. If it does not, a different amount, structure, or preparation plan may be needed first.
The key shift is this: You are no longer being evaluated only on personal income. The performance of the asset becomes a central part of the review.
If you are trying to understand whether a property might qualify under DSCR, it helps to look at it through that lens early. It changes how you evaluate the deal before you even apply.